A Trading Workflow Guide for Consistent Execution
This trading workflow guide shows how to connect risk, planning, execution, review, and capital tracking into one disciplined operating system with clarity.
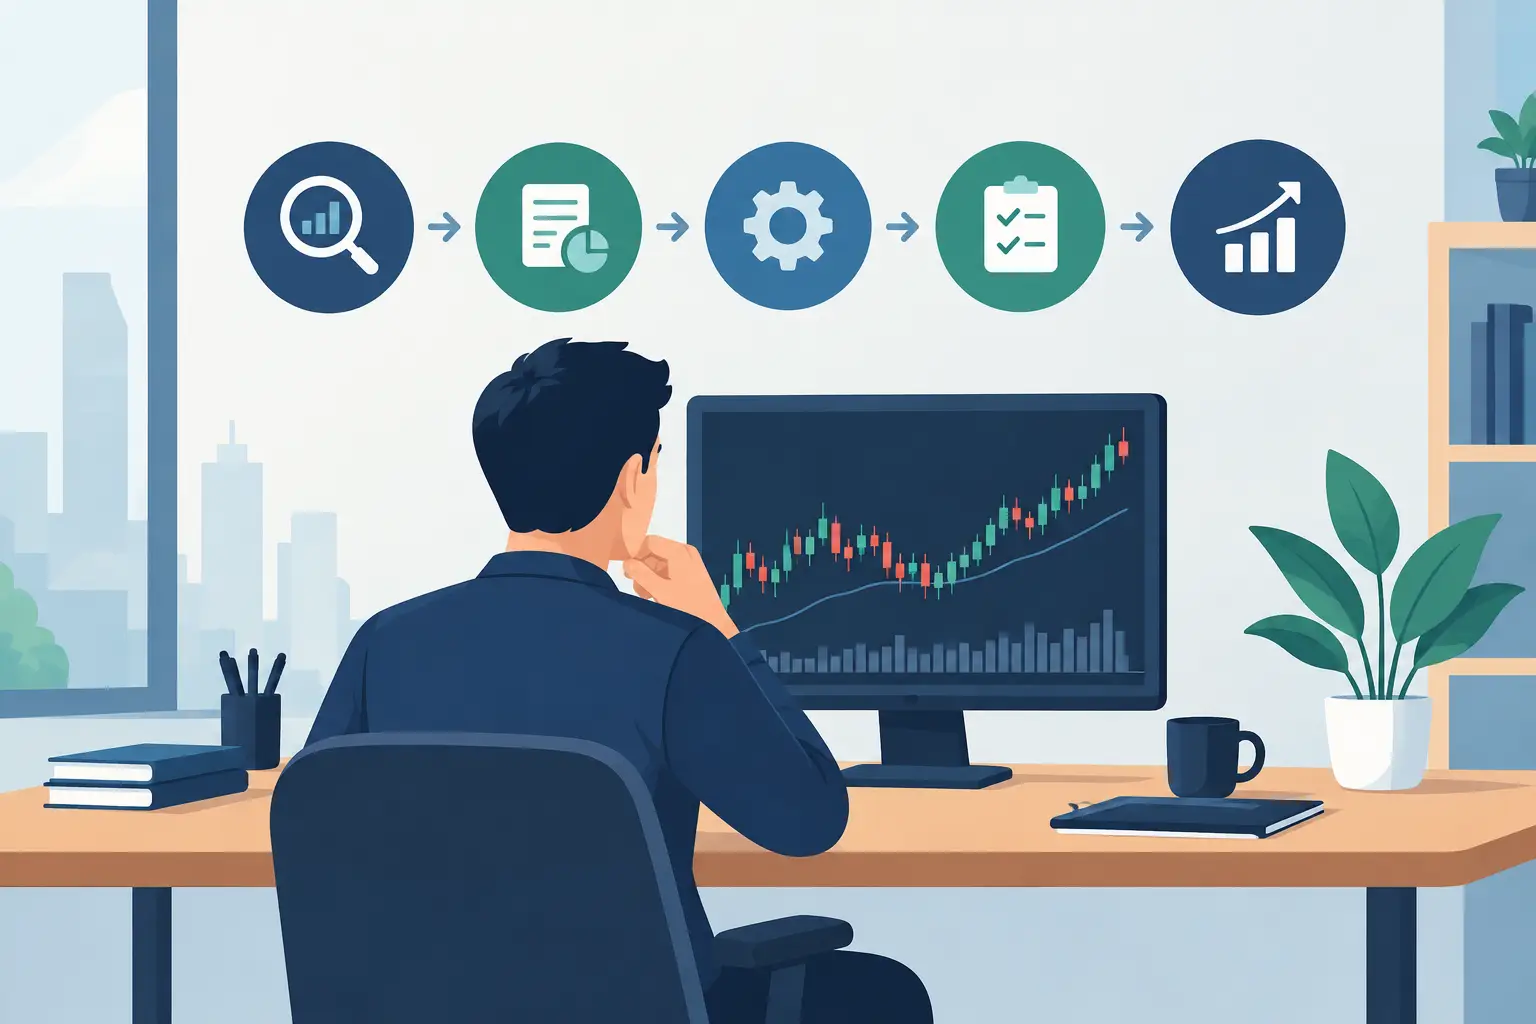
A profitable-looking trade can still be a process failure. If the position exceeded your planned risk, ignored your setup criteria, or was closed on impulse, the outcome does not validate the decision. That is why a trading workflow guide should start with control, not entries. Serious traders need a repeatable operating sequence that connects risk, planning, execution, review, and capital management.
Fragmented tools create fragmented decisions. A charting platform may show the setup, a spreadsheet may hold risk limits, a journal may capture notes, and a calendar may track events. When those records do not work together, it becomes difficult to see whether your results came from a sound strategy or from inconsistent behavior. One connected workflow turns activity into evidence.
What a Trading Workflow Must Control
A trading workflow is not a rigid routine that forces every trader into the same market style. A day trader managing fast intraday exposure needs different timing than a position investor managing multi-week risk. The purpose is the same in both cases: define the decision before capital is exposed, document what happened, and use the record to improve the next decision.
The workflow should answer five operational questions:
- What risk is allowed before the trade is placed?
- What setup or thesis justifies the position?
- What market conditions affect the decision?
- Was the trade executed according to plan?
- What does the result reveal about the strategy and the trader?
Without clear answers, performance analysis becomes shallow. A win rate alone cannot tell you whether position sizing was responsible, whether certain market conditions improve expectancy, or whether losses came from normal variance versus preventable rule violations.
Build the Trading Workflow Around Risk First
Risk management belongs at the beginning because every later step depends on it. Before the market opens or a swing position is considered, establish the boundaries that cannot be negotiated: maximum risk per trade, daily loss limit, account drawdown limit, maximum concurrent exposure, and any prop firm restrictions.
These rules must be measurable. “Trade smaller when conditions are difficult” is not a rule. “Reduce risk by 50% after two consecutive losses or when daily drawdown reaches 1%” can be tracked and reviewed. The right numbers depend on account size, strategy volatility, holding period, and external constraints. A funded trader may need tighter daily controls than an investor building a diversified portfolio, while both still need predefined exposure limits.
Risk rules also need a response protocol. Decide what happens when a limit is reached. Does trading stop for the session? Is size reduced for the next day? Does a breach require a formal review before new trades are allowed? A rule without a defined consequence is only a preference.
Connect Position Size to Trade Structure
Position size should follow the location of the stop and the amount of capital at risk, not confidence in the idea. Confidence can be useful when ranking valid setups, but it is not a substitute for a defined loss point.
For each trade, record the entry, invalidation level, planned risk, size, target or exit framework, and expected reward relative to risk. This creates a reference point for execution review. If you moved the stop, added to a losing trade, or took profit before the plan allowed, the deviation becomes visible instead of disappearing inside the final P&L.
Plan Activity Before the Session Begins
Planning is where market context meets strategy criteria. For an intraday trader, this may include economic releases, earnings, opening conditions, key price levels, liquidity expectations, and a watchlist ranked by opportunity. For swing and position traders, planning may focus more on trend structure, sector behavior, portfolio correlation, macro events, and scheduled catalysts.
The goal is not to predict every price movement. It is to define what you will pay attention to and what would make a trade valid. A planned watchlist reduces reactive scanning. A documented market thesis prevents you from rewriting the reason for a trade after the fact.
Your plan should also identify no-trade conditions. Low liquidity, major news risk, a daily loss limit, poor sleep, or a market environment that does not fit your strategy can all justify standing aside. Professional discipline includes preserving capital when the required conditions are absent.
Use a Strategy Library, Not Memory
A setup that exists only in your head cannot be tested consistently. Document each strategy with its market conditions, entry trigger, invalidation point, management rules, typical holding time, and known failure patterns. Include chart examples when useful.
This matters when performance changes. If a strategy underperforms, you need to know whether the edge weakened, the market regime shifted, or execution drifted from the documented rules. Without a stable strategy definition, every review becomes subjective.
Execute and Record at the Point of Decision
The execution stage should be simple because complexity increases errors when markets move quickly. Use the pre-trade plan to confirm the setup, calculate size, place the trade, and manage it according to the stated rules. Avoid creating new rules in the middle of a position unless the strategy explicitly allows for adaptive management.
Record the trade while the decision is fresh. Capture the setup, entry and exit data, position size, direction, market context, planned risk, realized result, and a brief note on execution quality. A chart snapshot before and after the trade often reveals information that numbers cannot, such as chasing an extended move or entering directly into a major level.
Trade journaling is not an administrative task to postpone until the weekend. Delayed notes become incomplete notes. The more precise the record, the more useful the analysis.
Review Performance in Layers
A good review process separates outcome from quality. A well-executed loss may be acceptable. A poorly managed gain may reveal a problem that will eventually damage the account. Review trades first by rule adherence, then by strategy performance, then by portfolio or account-level impact.
At the individual level, ask whether the entry, size, stop, and exit followed the plan. At the strategy level, examine expectancy, average win and loss, profit factor, win rate, hold time, and results by market condition. At the account level, monitor drawdown, exposure concentration, daily consistency, and the effect of fees or financing costs.
Break results into useful segments. Compare performance by setup, time of day, day of week, market direction, instrument, and trade duration. A day trader may find that the first hour produces most rule-following opportunities while midday activity creates avoidable losses. A swing trader may discover that a strategy works in trending markets but loses its edge during range-bound conditions.
The point is not to search for flattering statistics. It is to identify decisions that deserve more capital, less capital, or no capital at all.
Turn Findings Into One Process Change
Review becomes ineffective when it produces a long list of vague intentions. Choose one or two measurable adjustments for the next review period. For example, eliminate entries taken before a defined confirmation, reduce size on a setup with weak expectancy, or stop trading after a second execution error.
Then track the change. If the adjustment improves adherence and results over a meaningful sample, make it part of the operating rules. If it does not, investigate further rather than forcing a conclusion from a handful of trades.
Practice Before You Change Live Risk
Historical replay and chart review provide a controlled environment for testing decisions. They are especially useful when developing a new setup, practicing trade management, or studying how a strategy behaves through different market regimes. Replay cannot duplicate every live trading pressure, but it can expose whether the rules are clear enough to execute repeatedly.
Use practice to answer specific questions. Can you identify the setup consistently? Does the stop placement produce acceptable reward-to-risk characteristics? How often does the target get reached before a management rule would exit? A test with defined criteria is more valuable than scrolling through charts looking for confirmation.
When changes survive replay and forward observation, introduce them to live trading with controlled size. This protects capital while the evidence develops.
Make Capital Management Part of the Same System
Trading performance does not exist separately from personal or business finances. A trader who depends on trading income for near-term expenses may take risk differently than planned. A portfolio manager needs visibility into cash, allocation, and correlated exposure beyond a single trade.
Track capital flows alongside trading results: deposits, withdrawals, account balances, reserved tax funds, subscriptions, and other trading-related expenses. This creates a clearer view of net progress and prevents gross P&L from becoming the only measure that matters.
Cobra Trading System is built around this connected model: risk rules, trading records, strategy documentation, market analysis, performance statistics, and capital visibility in one operating environment. The value is not simply having more data. It is being able to connect a result to the decision process that created it.
A disciplined workflow will not remove uncertainty from markets. It gives uncertainty a structure. When every trade follows a defined path from risk to review, improvement stops depending on memory, emotion, or the latest outcome and starts depending on evidence.